What Is DeFi? Decentralised Finance Explained for India
What is DeFi? A plain-English guide to decentralised finance: lending, DEXs, stablecoins and yield, the real risks, and how DeFi income is taxed in India.
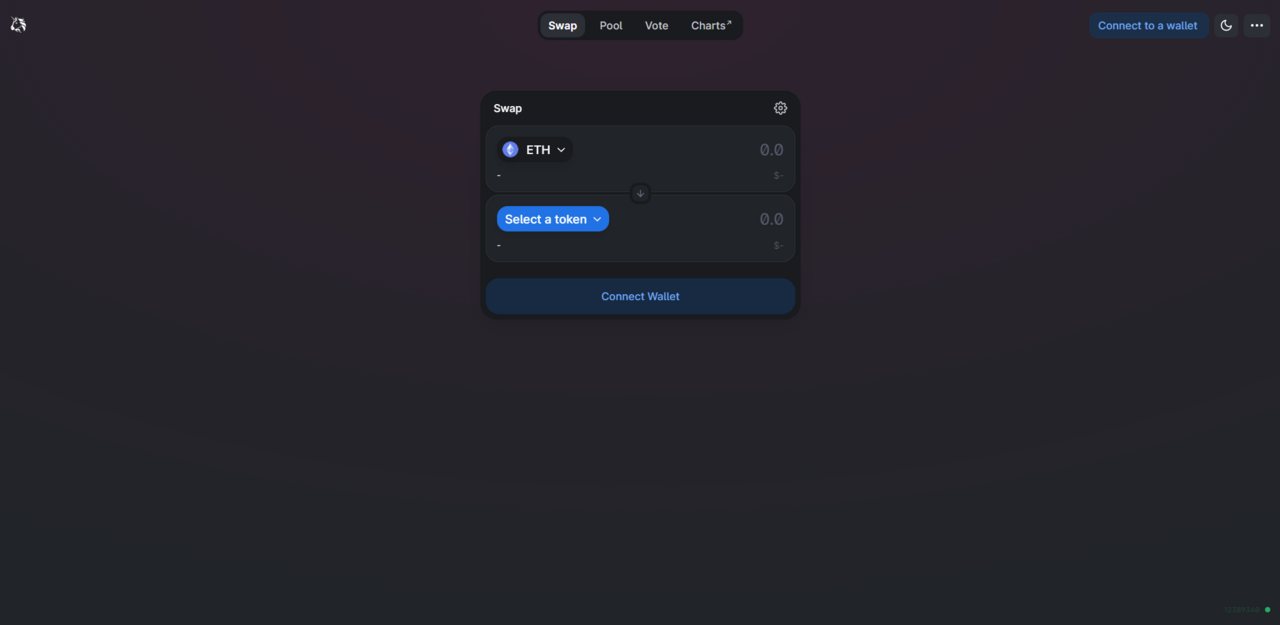
DeFi, or decentralised finance, means financial services (trading, lending, borrowing and earning interest) that run on blockchains through smart contracts instead of banks or brokers. You connect a crypto wallet, and code handles the transaction without a company holding your money. It offers open, 24/7 access, but also new risks such as hacks, bugs and sudden liquidations.
Key takeaways
- DeFi apps are smart contracts, mostly on Ethereum and networks like Solana and Ethereum layer-2s.
- The main uses are decentralised exchanges (like Uniswap), lending markets (like Aave), stablecoins and yield strategies.
- You keep custody of your assets in your own wallet, which also means there is no customer support if you make a mistake.
- Key risks: smart-contract hacks, liquidations, stablecoin failures, scam tokens and phishing.
- In India every swap is a taxable VDA transfer at 30%; DeFi interest may be taxed as income at slab rates.
How DeFi works
In traditional finance, a bank or broker sits in the middle, holds your money and decides who can use its services. In DeFi, that middle layer is replaced by smart contracts: programs deployed on a blockchain that anyone can inspect and use. You connect a self-custody wallet such as MetaMask, approve a transaction, and the contract executes it. No account opening, no office hours.
Most DeFi runs on Ethereum and networks that settle to it, though Solana, BNB Chain and others host large ecosystems too. Fees are paid in the network’s native coin, such as ETH.
The main building blocks of DeFi
Decentralised exchanges (DEXs)
A DEX lets you swap one token for another directly from your wallet. Instead of an order book, most use liquidity pools: users deposit pairs of tokens, and a formula sets the price. Uniswap is the best-known DEX; its UNI token gives holders a say in governance. See our UNI coin page.
Lending and borrowing
Lending protocols let you deposit crypto to earn interest, or borrow against collateral. Loans are over-collateralised: to borrow ₹50,000 worth of stablecoins you might need to lock up ₹75,000 or more of ETH. If your collateral’s value falls too far, it is automatically sold (liquidated). Aave is one of the largest lending protocols; see our AAVE coin page.
Stablecoins
Stablecoins such as USDT and USDC aim to track the US dollar, and they are the base currency of most DeFi activity. Some are backed by cash and bonds held by a company; others are backed by crypto collateral or algorithms, and these can fail, as the TerraUSD collapse showed in 2022.
Yield, staking and liquidity providing
“Yield” in DeFi comes from real sources: borrowers paying interest, traders paying swap fees, or protocols paying rewards in their own tokens. Very high advertised yields usually come from token rewards that can lose value fast.
DeFi vs traditional finance
| Feature | Traditional finance (bank/broker) | DeFi |
|---|---|---|
| Who holds your money | The institution | You, in your own wallet |
| Access | KYC, office hours, eligibility rules | Anyone with a wallet, 24/7 |
| Transparency | Internal records | All transactions visible on-chain |
| Protection | Regulation, deposit insurance (in India, DICGC for bank deposits) | Usually none |
| If something goes wrong | Customer support, ombudsman, courts | Often no recourse |
| Main risks | Institution failure, fees, delays | Hacks, bugs, liquidation, user error |
The real risks of DeFi
- Smart-contract bugs and hacks: billions of dollars have been stolen from DeFi protocols and cross-chain bridges over the years. Audits reduce but do not remove this risk.
- Liquidation: in a sharp crash, borrowers can lose their collateral within minutes.
- Impermanent loss: liquidity providers can end up with less value than if they had simply held their tokens.
- Stablecoin de-pegs: a stablecoin that loses its peg can wipe out “safe” yields.
- Scams and phishing: fake DEX sites, malicious token approvals and rug-pulled tokens are common. Read our guide to spotting crypto scams in India.
- Self-custody mistakes: lose your seed phrase or send to the wrong address and nobody can reverse it.
How DeFi is taxed in India
India has no DeFi-specific law, so the general virtual digital asset rules apply, and some areas are unclear. In broad terms:
- Swaps are transfers. Swapping ETH for USDC on a DEX is treated as a transfer of a VDA, so any gain is taxed at a flat 30% (plus cess) under the regime introduced as Section 115BBH. Losses cannot be set off or carried forward.
- TDS still applies in principle. The 1% TDS introduced as Section 194S applies to VDA transfers above the threshold. On a DEX there is no Indian intermediary to deduct it, so the compliance burden can fall on the buyer. That is one reason many Indians avoid heavy DEX use.
- Interest and rewards. Lending interest, staking and liquidity rewards are generally treated as income when received (often at your slab rate) and then as VDA with that value as cost when later sold at 30%. Treatment can vary, so get professional advice.
These rules continue in FY 2026-27, now under the Income-tax Act, 2025, which renumbered the sections from 1 April 2026 without changing rates. Keep a record of every transaction (wallet explorers make that possible) and estimate your liability with our crypto tax calculator. Our full crypto tax guide covers the basics.
How to try DeFi safely
- Learn the basics on a centralised Indian exchange first, then move a small amount to a self-custody wallet.
- Write your seed phrase on paper, store it offline, and never type it into a website.
- Bookmark official app URLs; do not click links from DMs or ads.
- Start with large, long-running protocols and small amounts.
- Review and revoke token approvals periodically.
Frequently asked questions
What is DeFi in simple words?
DeFi means banking-style services, such as swapping, lending, borrowing and earning interest, that are run by code on a blockchain instead of by a bank. You use it from your own crypto wallet.
Is DeFi legal in India?
Using DeFi is not specifically banned in India, but there is no DeFi-specific regulation or investor protection. Gains are taxed under the virtual digital asset rules, and you are responsible for your own compliance.
Is DeFi safe?
It carries more risk than a regulated exchange. Hacks, bugs, liquidations, scams and user error can cause total losses. Large, established protocols are generally less risky, but none is risk-free.
How do people earn money from DeFi?
By lending crypto for interest, providing liquidity for trading fees, staking, or earning token rewards. Returns vary and can be wiped out by falling token prices or hacks.
Is a DEX swap taxable in India?
Yes. Swapping one crypto for another is a transfer of a virtual digital asset, so any gain is taxed at 30%, and 1% TDS rules apply in principle.
This guide is educational and general in nature. It is not investment, tax or legal advice, and nothing here is a guarantee of any return. Crypto is volatile and you can lose money; only invest what you can afford to lose.
This article is AI-assisted, educational and general in nature. It is not financial advice and never a guarantee of profit. Every trade is at your own risk on your own exchange. See our risk disclosure and editorial policy.